SIP vs FD vs PPF: Where Should You Invest Rs 5,000 a Month?
Compare equity SIPs, bank FDs and PPF for a Rs 5,000 monthly investment using current rates, 2026 tax rules and worked numbers, then pick a split that suits your goal.
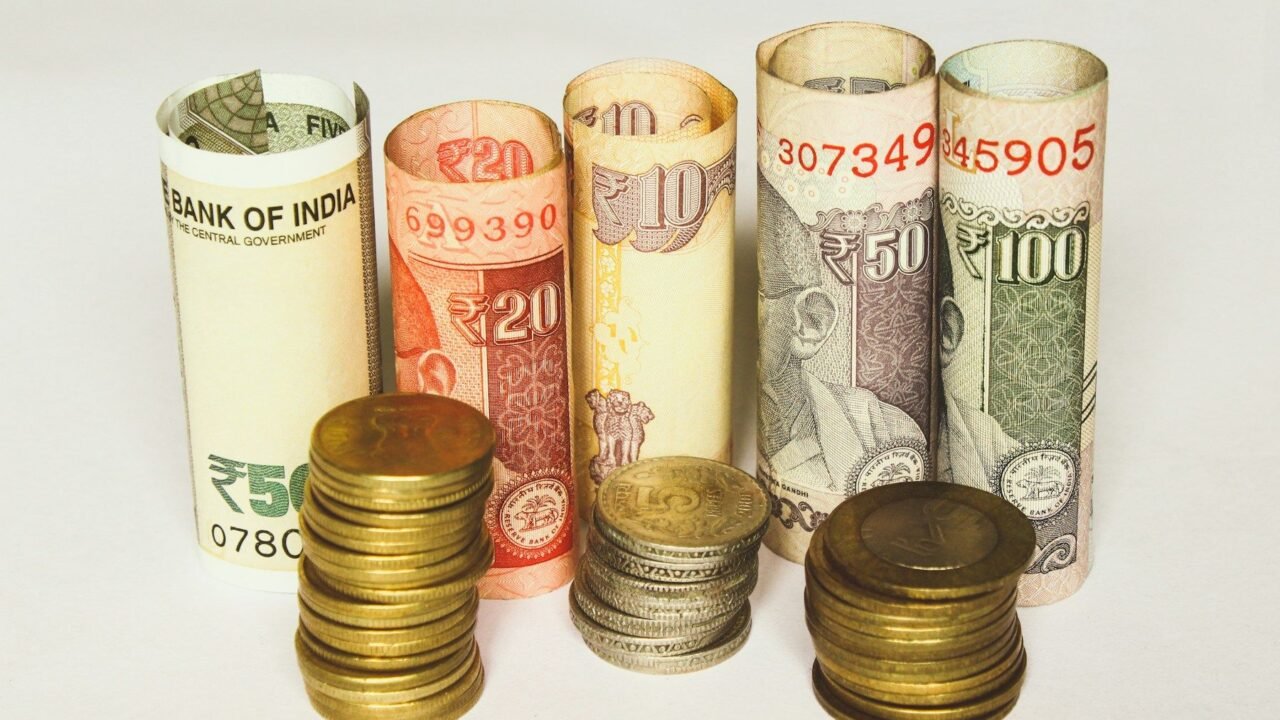
If you can set aside Rs 5,000 a month, the right home for it depends on when you need the money and how much short-term ups and downs you can stomach. For a goal 10 to 15 years away, an equity mutual fund SIP has historically had the best chance of beating inflation; PPF gives a guaranteed, tax-free 7.1 percent with a 15-year lock-in; and a bank FD or RD suits money you need within three years. This guide compares all three with real current rates, 2026 tax rules and worked numbers, and ends with a simple split that works for most salaried Indians.
Rates, tax rules and scheme conditions change. Figures below are as of late September 2026; check the official source before investing, and consider speaking to a SEBI-registered investment adviser for personal advice.
Key Takeaways
- PPF pays 7.1 percent a year for the July to September 2026 quarter, tax-free, with a 15-year lock-in and a limit of Rs 1.5 lakh a year.
- SBI’s regular FD rates are around 6.05 to 6.45 percent for the general public, and FD interest is fully taxable at your slab rate.
- Equity SIP returns are not guaranteed. Long-term gains above Rs 1.25 lakh a year are taxed at 12.5 percent; short-term gains at 20 percent.
- From 1 April 2026, the Section 80C deduction continues as Section 123 of the Income-tax Act, 2025, and applies only under the old tax regime.
- A practical split for Rs 5,000: build an emergency fund first, then divide between an equity SIP and PPF based on your goal’s time horizon.
The Three Options in One Table
| Feature | Equity mutual fund SIP | Bank FD / RD | PPF |
|---|---|---|---|
| Return | Market-linked, not guaranteed | Fixed at booking, about 6 to 6.5% at large banks | 7.1% (Jul to Sep 2026), revised quarterly |
| Risk | High in the short term; can fall 20 to 40% in bad years | Very low; deposits currently insured up to Rs 5 lakh per depositor per bank by DICGC | Very low; government-backed |
| Lock-in | None (ELSS: 3 years) | Your chosen tenure; penalty on early exit | 15 years, partial withdrawal from year 7 |
| Minimum | Rs 100 to Rs 500 a month in most funds | Rs 100 to Rs 1,000 depending on bank | Rs 500 a year |
| Maximum | No limit | No limit | Rs 1.5 lakh a year |
| Tax on returns | LTCG 12.5% above Rs 1.25 lakh; STCG 20% | Fully taxable at slab rate; TDS above Rs 50,000 interest a year | Fully tax-free (EEE) |
| Tax deduction on investment | Only ELSS, old regime only | Only 5-year tax-saver FD, old regime only | Yes, old regime only |
| Best for | Goals 7+ years away | Goals under 3 years, emergency fund | Safe long-term corpus, retirement |
PPF: Guaranteed, Tax-Free, But Locked
The Public Provident Fund is a government savings scheme you can open at a post office or any authorised bank. The finance ministry kept the PPF rate at 7.1 percent for the July to September 2026 quarter, as reported by Business Today. The rate for October to December is usually announced in the last days of September, so check for the update.
Key PPF rules
- Minimum Rs 500 and maximum Rs 1.5 lakh in a financial year.
- Tenure is 15 years, which can be extended in blocks of 5 years.
- Interest is calculated on the lowest balance between the 5th and the last day of each month. Deposit before the 5th to earn interest for that month.
- Interest is compounded yearly and credited at the end of the financial year.
- Loans are available from the third financial year, and partial withdrawals from the seventh.
- Returns are fully tax-free, and the investment qualifies for the deduction formerly known as 80C (now Section 123) under the old regime.
Who PPF suits
PPF is ideal for someone who wants a safe, tax-free corpus for retirement or a child’s higher education 15 years away, and who won’t be tempted to touch the money. Its weakness is liquidity: you cannot pull the full amount out early except in limited cases.
Bank FD and RD: Safe, Liquid, Taxable
For monthly investing, what you actually open is a recurring deposit (RD), which works like a monthly FD. Rates are similar to FDs of the same tenure.
Bank deposit rates have come down since the RBI began cutting the repo rate in 2025. According to Zee Business’s September 2026 comparison, SBI offers about 6.25 percent for one year and 6.05 percent for five years to the general public, with a maximum of 6.45 percent on its 444-day Amrit Vrishti scheme. Senior citizens get higher rates. Small finance banks pay more, but check that the bank is covered by DICGC deposit insurance and don’t park more than Rs 5 lakh in any single bank.
The tax catch
FD and RD interest is added to your income and taxed at your slab rate. Banks deduct TDS at 10 percent once interest from that bank crosses Rs 50,000 in a financial year (Rs 1 lakh for senior citizens), and at a higher rate if your PAN is not linked. If you are in the 30 percent bracket, a 6.25 percent FD effectively gives you about 4.4 percent after tax, which is below typical inflation.
Who FD and RD suit
Your emergency fund, a goal within one to three years (a bike, a wedding next year, a house deposit), and anyone in a low tax bracket or no-tax situation who cannot afford any fall in value.
Equity SIP: Highest Potential, No Guarantee
A Systematic Investment Plan puts a fixed amount into a mutual fund every month. With an equity fund, your money buys shares of companies, so the value moves with the stock market.
What to expect
Over long periods, diversified Indian equity has generally delivered higher returns than FDs and PPF, but with sharp falls along the way. It is normal for an equity SIP to show a loss after one or two years. The benefit of a SIP is that you buy more units when prices are low, which averages your cost over time. Past returns do not guarantee future returns, and no one can promise you 12 percent.
Tax on equity funds
- Units held more than 12 months: long-term capital gains taxed at 12.5 percent, but only on gains above Rs 1.25 lakh in a financial year across all your equity investments.
- Units held 12 months or less: short-term gains taxed at 20 percent.
- Each monthly SIP instalment has its own 12-month clock.
Which funds for a beginner
For a first SIP, a low-cost Nifty 50 or Nifty 100 index fund, or a flexi-cap fund, is easier to hold through ups and downs than a small-cap or sectoral fund. Choose the direct plan of a fund to avoid distributor commission, and use your mutual fund’s own app, the MF Central platform or a SEBI-registered platform to invest.
What Rs 5,000 a Month Can Grow To
The table below shows illustrative values for Rs 5,000 a month. PPF uses the current 7.1 percent, held constant. RD uses 6.25 percent compounded quarterly. SIP values use assumed annual returns of 8, 10 and 12 percent purely for illustration; actual equity returns can be higher, lower or negative over any period.
| Period (you invest) | RD at 6.25% (pre-tax) | PPF at 7.1% (tax-free) | SIP at 8% | SIP at 10% | SIP at 12% |
|---|---|---|---|---|---|
| 5 years (Rs 3 lakh) | Rs 3.53 lakh | Rs 3.59 lakh | Rs 3.67 lakh | Rs 3.86 lakh | Rs 4.06 lakh |
| 10 years (Rs 6 lakh) | Rs 8.33 lakh | Rs 8.65 lakh | Rs 9.06 lakh | Rs 10.07 lakh | Rs 11.20 lakh |
| 15 years (Rs 9 lakh) | Rs 14.89 lakh | Rs 15.78 lakh | Rs 16.99 lakh | Rs 20.08 lakh | Rs 23.80 lakh |
After tax, the picture shifts further
Take the 15-year column. For someone in the 30 percent bracket paying tax on RD interest every year, the Rs 14.89 lakh RD shrinks to roughly Rs 12.7 lakh. The PPF amount stays at Rs 15.78 lakh because it is tax-free. For the SIP at an assumed 10 percent, if you redeemed everything in one financial year, tax at 12.5 percent on gains above Rs 1.25 lakh would be about Rs 1.23 lakh, leaving roughly Rs 18.85 lakh. Redeeming across two or three financial years would lower the tax further, since each year gets its own Rs 1.25 lakh exemption.
Over five years the gap between the three is small. Over fifteen years it becomes large. That is the core lesson: time horizon matters more than the product.
Old vs New Tax Regime: Does the Deduction Matter?
The new Income-tax Act, 2025 came into force on 1 April 2026. The familiar Section 80C deduction of up to Rs 1.5 lakh continues as Section 123, as explained by Business Today, covering PPF, ELSS, tax-saver FDs, EPF, life insurance premiums and more.
The catch: it is available only under the old regime. The new regime, which is the default and has lower slab rates, does not allow this deduction. Most salaried people with modest deductions now find the new regime cheaper, in which case:
- PPF still makes sense for its tax-free returns and safety, but not for saving tax on the investment.
- ELSS loses its main advantage; a regular index or flexi-cap fund with no lock-in may be more flexible.
- Tax-saver FDs lose their purpose entirely.
If you still use the old regime because of a home loan, HRA and other deductions, putting part of your Rs 5,000 into PPF or ELSS helps fill the Rs 1.5 lakh limit.
A Simple Plan for Rs 5,000 a Month
There is no single right answer, but these splits work for most people. Adjust for your own goals.
Step 1: Emergency fund first
If you don’t have three to six months of expenses set aside, put the full Rs 5,000 into an RD or a sweep-in savings account until you do. Investing in equity without an emergency fund often ends with selling at a loss when an unexpected bill arrives.
Step 2: Choose a split by goal
- Goal 10+ years away (retirement, child’s education): Rs 3,000 in an equity index fund SIP, Rs 2,000 in PPF. You get growth plus a guaranteed tax-free base.
- Goal 5 to 7 years away (house down payment): Rs 2,500 in an equity or balanced advantage fund, Rs 2,500 in PPF or RD. Start moving equity money into safer options two years before the goal.
- Goal within 3 years: Rs 5,000 in RD. Equity is too volatile for short goals.
- You cannot sleep if your investment falls: Rs 4,000 in PPF, Rs 1,000 in an index fund SIP to get used to market movements.
Step 3: Step it up every year
Raise the monthly amount by 10 percent each time you get a raise. Going from Rs 5,000 to Rs 5,500 to Rs 6,050 and so on has a larger effect on the final corpus than chasing a slightly better fund.
Mistakes to Avoid
- Stopping SIPs when markets fall. That is exactly when your SIP buys more units cheaply.
- Breaking FDs for spending. Premature withdrawal penalties cut your return.
- Missing the PPF 5th-of-month deadline. A deposit on the 6th earns no interest for that month.
- Buying insurance-cum-investment plans as a substitute. Keep term insurance and investments separate.
- Chasing last year’s top fund. Recent top performers often slip down the rankings. Consistency and low cost matter more.
Frequently Asked Questions
What is the current PPF interest rate?
PPF pays 7.1 percent a year for the July to September 2026 quarter. The government reviews small savings rates every quarter, so check the rate announced for October to December 2026.
Is SIP better than FD for Rs 5,000 a month?
For goals more than seven years away, an equity SIP has historically had a better chance of beating inflation than an FD, but with no guarantee and with temporary losses along the way. For goals within three years, an FD or RD is safer.
Can I claim PPF under the new tax regime?
No. The deduction for PPF (formerly Section 80C, now Section 123 from 1 April 2026) is available only under the old regime. PPF interest and maturity remain tax-free under both regimes.
How much tax do I pay on SIP returns?
For equity funds held over 12 months, gains above Rs 1.25 lakh in a financial year are taxed at 12.5 percent. Gains on units held 12 months or less are taxed at 20 percent.
Is TDS deducted on FD interest?
Yes, at 10 percent once your interest from one bank crosses Rs 50,000 in a financial year, or Rs 1 lakh for senior citizens. If your total income is below the taxable limit, you can submit the prescribed declaration to your bank to avoid TDS.
Can I invest in all three at once?
Yes, and many people should. An RD for the emergency fund, PPF for guaranteed long-term savings and an equity SIP for growth together balance safety, tax efficiency and returns.
Start Small, Stay Consistent
Rs 5,000 a month is a meaningful start. The biggest difference comes not from picking the perfect product but from starting now, matching each rupee to a goal, and continuing through market ups and downs. Build your emergency fund in an RD, lock in a tax-free base with PPF, let an equity SIP do the long-term heavy lifting, and review your plan once a year when rates and rules change.